Fertilizer Market: Price Correction Creates a Window for Purchases
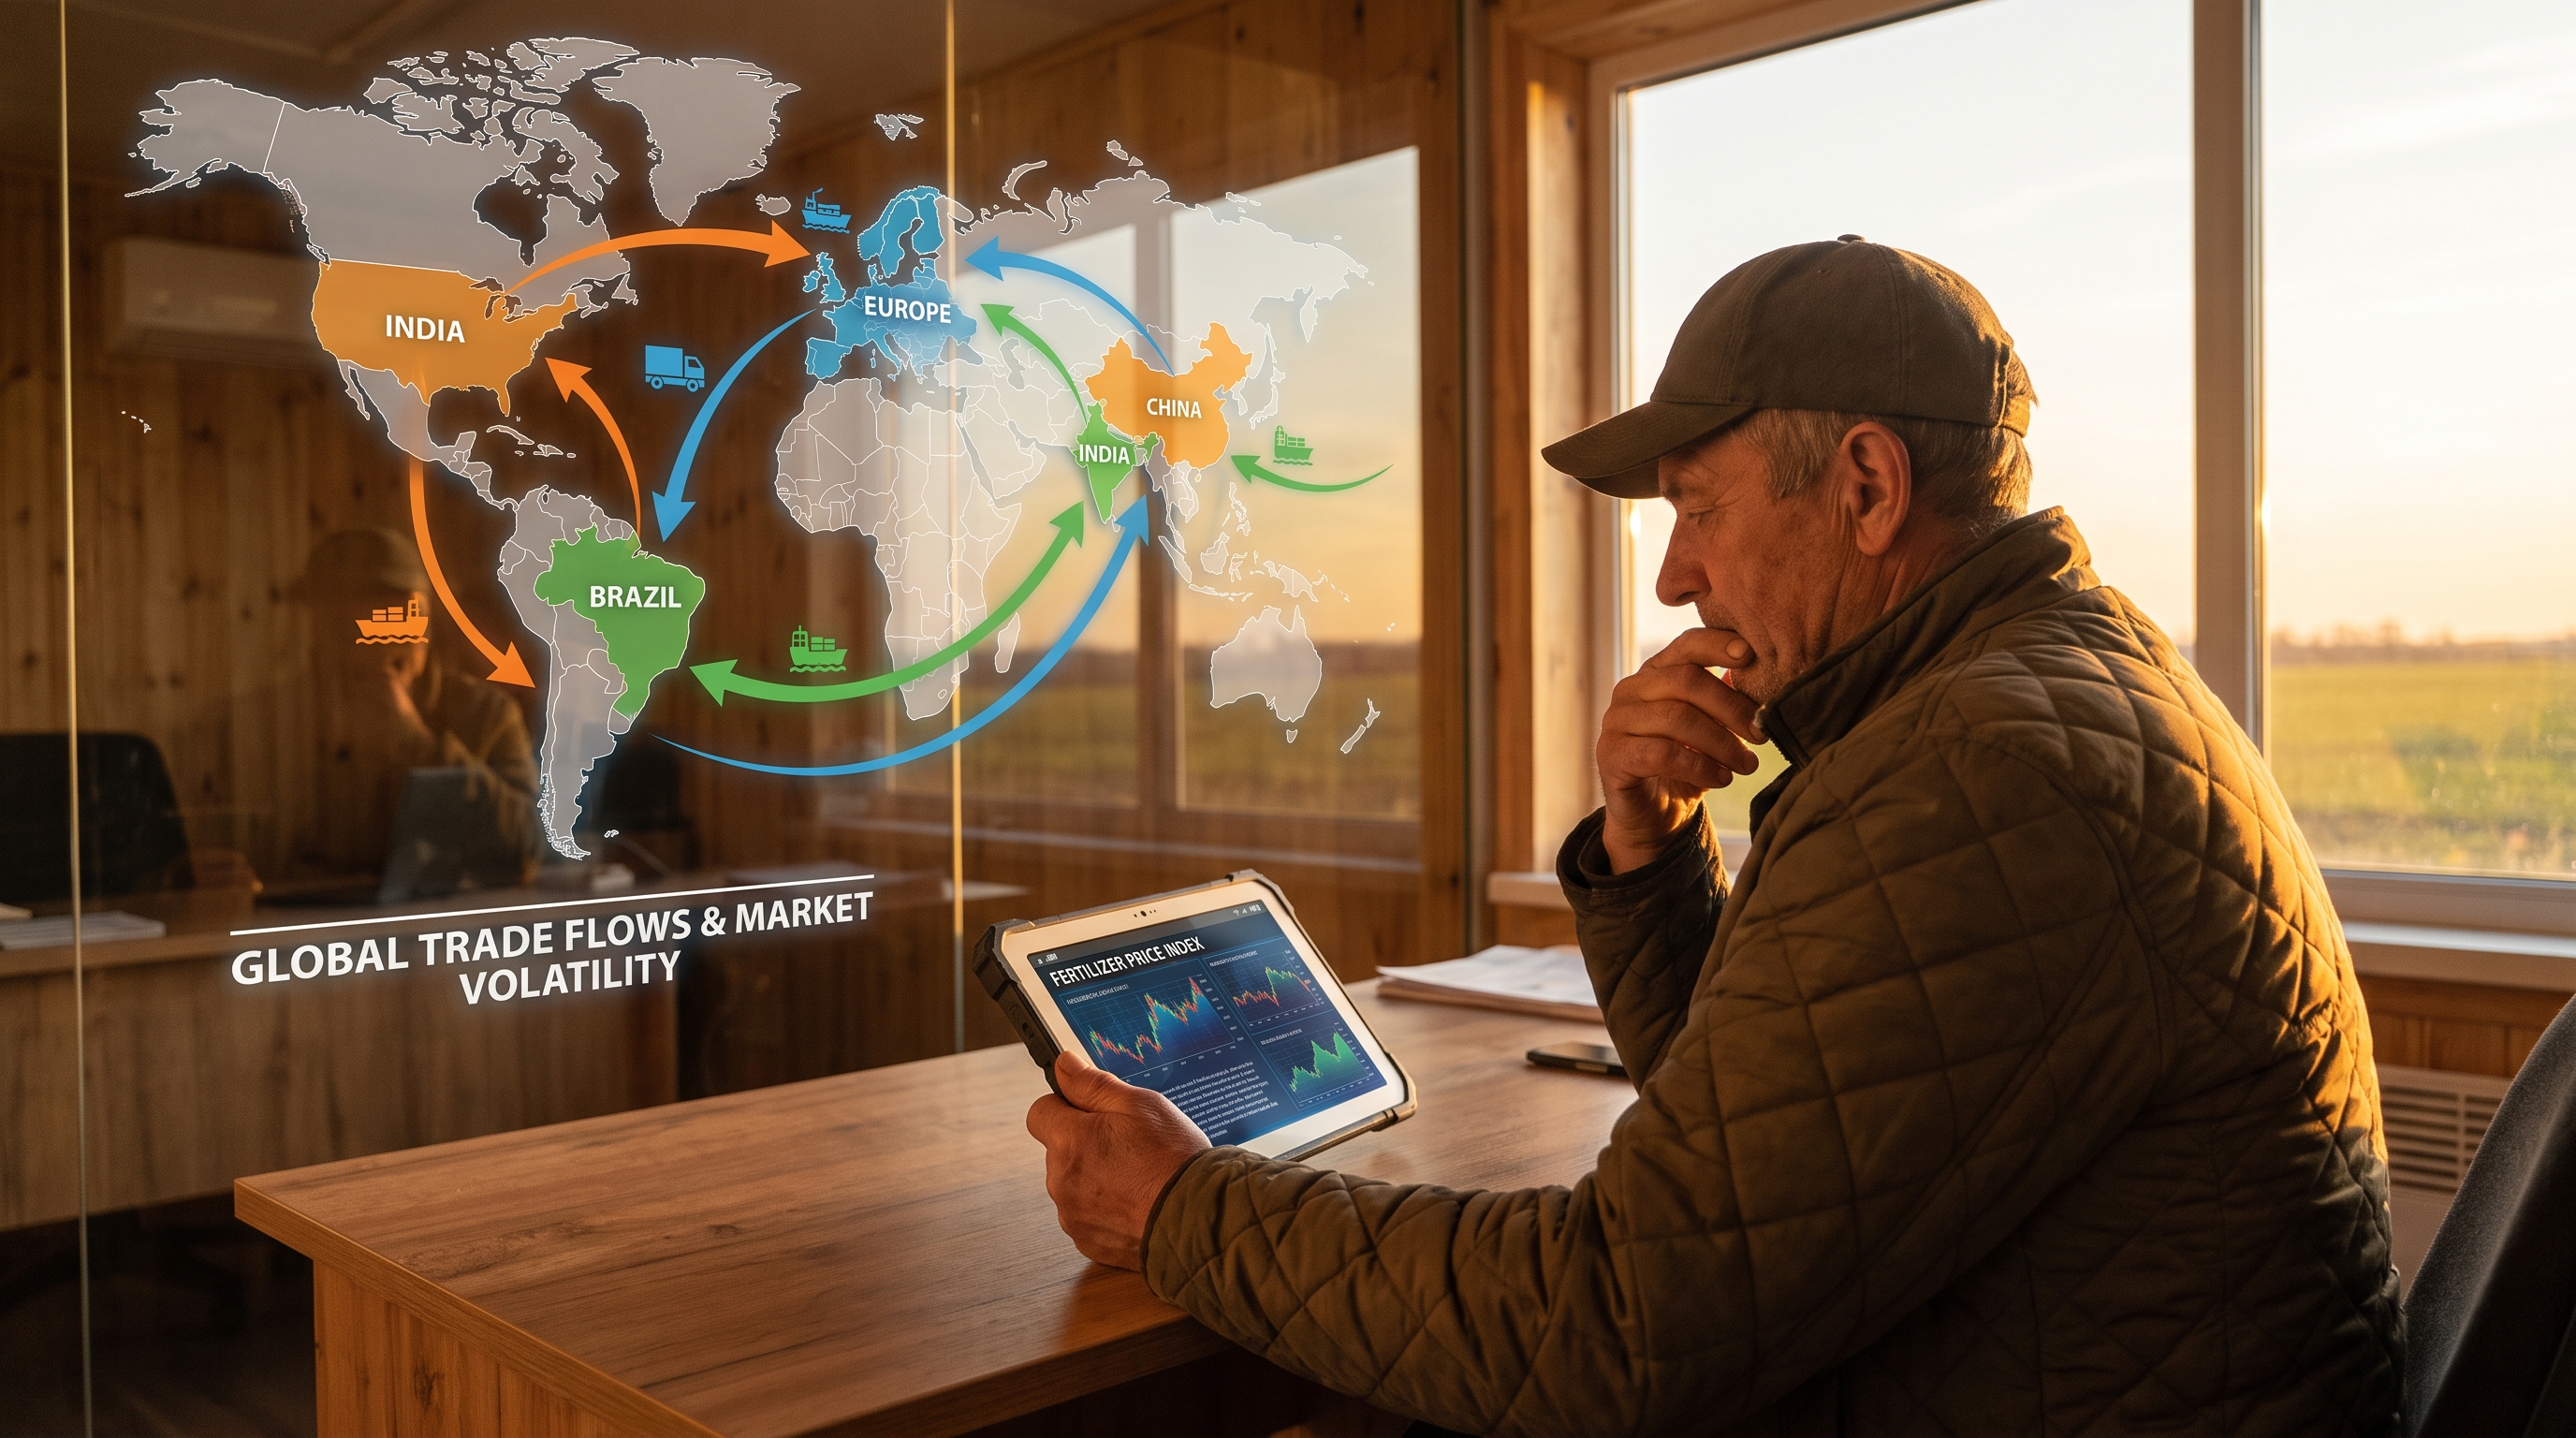
The global nitrogen fertilizer market has undergone a significant price correction, largely driven by the results of a major Indian tender that pressured urea quotations downward. This global trend opens a tactical window of opportunity for Ukrainian farmers to replenish their stocks ahead of the autumn sowing campaign and for the upcoming season. However, the situation remains dynamic, and a range of factors, from logistical challenges in Europe to renewed demand in Latin America, could shift the market balance in the coming months.
For Ukrainian agricultural enterprises operating under economic uncertainty, understanding these global movements is key to optimizing costs and ensuring the stability of future harvests. The current price dip may be short-lived, making risk analysis and timely decision-making critically important. Experienced importers are already intensifying their market monitoring to offer farmers the most favorable terms during this period of volatility.
Key Trends in the Global Nitrogen Fertilizer Market
The primary downward pressure on prices originated from Asia, where the Indian tender forced suppliers from the Middle East and China to compete by offering lower prices. This triggered a chain reaction worldwide. Markets that traditionally benchmark against Middle Eastern prices, such as Brazil, also experienced a softening. Traders in Latin America adopted a wait-and-see approach, seeking further clarity, which temporarily dampened purchasing activity.
Simultaneously, several factors are preventing a further price collapse. First, demand from major agricultural markets like Brazil and the United States is expected to pick up soon, which will support prices. Second, China's export policy remains a key unpredictable variable. Although Beijing periodically releases volumes to the global market, its priority is to secure domestic supply, which could lead to sudden export restrictions.
Logistical problems in Europe also warrant special attention. Record-low water levels on the Rhine River are severely complicating the transport of goods, including fertilizers, from the ARA ports (Amsterdam-Rotterdam-Antwerp) to inland destinations. This increases logistics costs and could create localized shortages in Germany and France, indirectly affecting the broader European market. Heightened tensions in the Black Sea are also driving up insurance and freight rates, posing additional risks for imports into Ukraine.
Market Analysis and Implications for Ukraine
For Ukraine, which is heavily dependent on fertilizer imports, the current global market conditions are favorable. According to industry data, fertilizer imports into Ukraine increased in the first few months of 2026, yet the market still faces a deficit in certain products, particularly NPK and phosphate fertilizers. This means that any drop in global prices allows traders to secure more advantageous contracts and partially offset high logistics costs.
However, farmers should remain cautious. The World Bank notes in its outlook that while agricultural commodity prices are generally stabilizing, the cost of inputs like fertilizers will remain volatile due to geopolitical risks and energy prices. This supports the view that the current drop in urea prices is more of a temporary correction than a long-term trend. Demand from India, Brazil, and the US will inevitably recover, pushing prices up again.
Another crucial aspect for Ukraine is the preparation for sowing winter crops. According to the Ukrainian Hydrometeorological Center, many regions are experiencing a soil moisture deficit, creating unfavorable conditions for sowing winter rapeseed. Under these conditions, providing plants with accessible nitrogen in the early stages of development becomes even more critical for shaping the future harvest. Timely procurement of fertilizers at the current, more attractive prices will not only save costs but also help mitigate agronomic risks.
Strategic Outlook and Recommendations
In the next 1-3 months, the market is likely to enter a consolidation phase. Urea prices are expected to stabilize at current levels, followed by a gradual recovery. The key drivers of this rebound will be seasonal demand in North and South America, as well as potential export restrictions from China. Logistical bottlenecks in Europe and the Black Sea will continue to exert upward pressure on delivery costs.
For Ukrainian farmers, this means that August and September represent an optimal period for making strategic purchases of nitrogen fertilizers. Postponing this decision carries the risk of facing higher prices and limited product availability later. Given the USDA's forecast of reduced grain exports from Ukraine due to logistical hurdles, optimizing production costs has become the number one priority.
In such a volatile environment, partnering with reliable and experienced importers who have diversified supply channels and a deep understanding of the global market is a key to success. Such partners can not only offer competitive prices but also ensure timely delivery, minimizing risks associated with logistics and market fluctuations. The current situation demands a proactive approach. Contact us for the latest information on fertilizer availability and pricing to develop the optimal procurement strategy for your farm.