Fertilizer Market: What Ukrainian Farmers Should Expect in Spring 2026
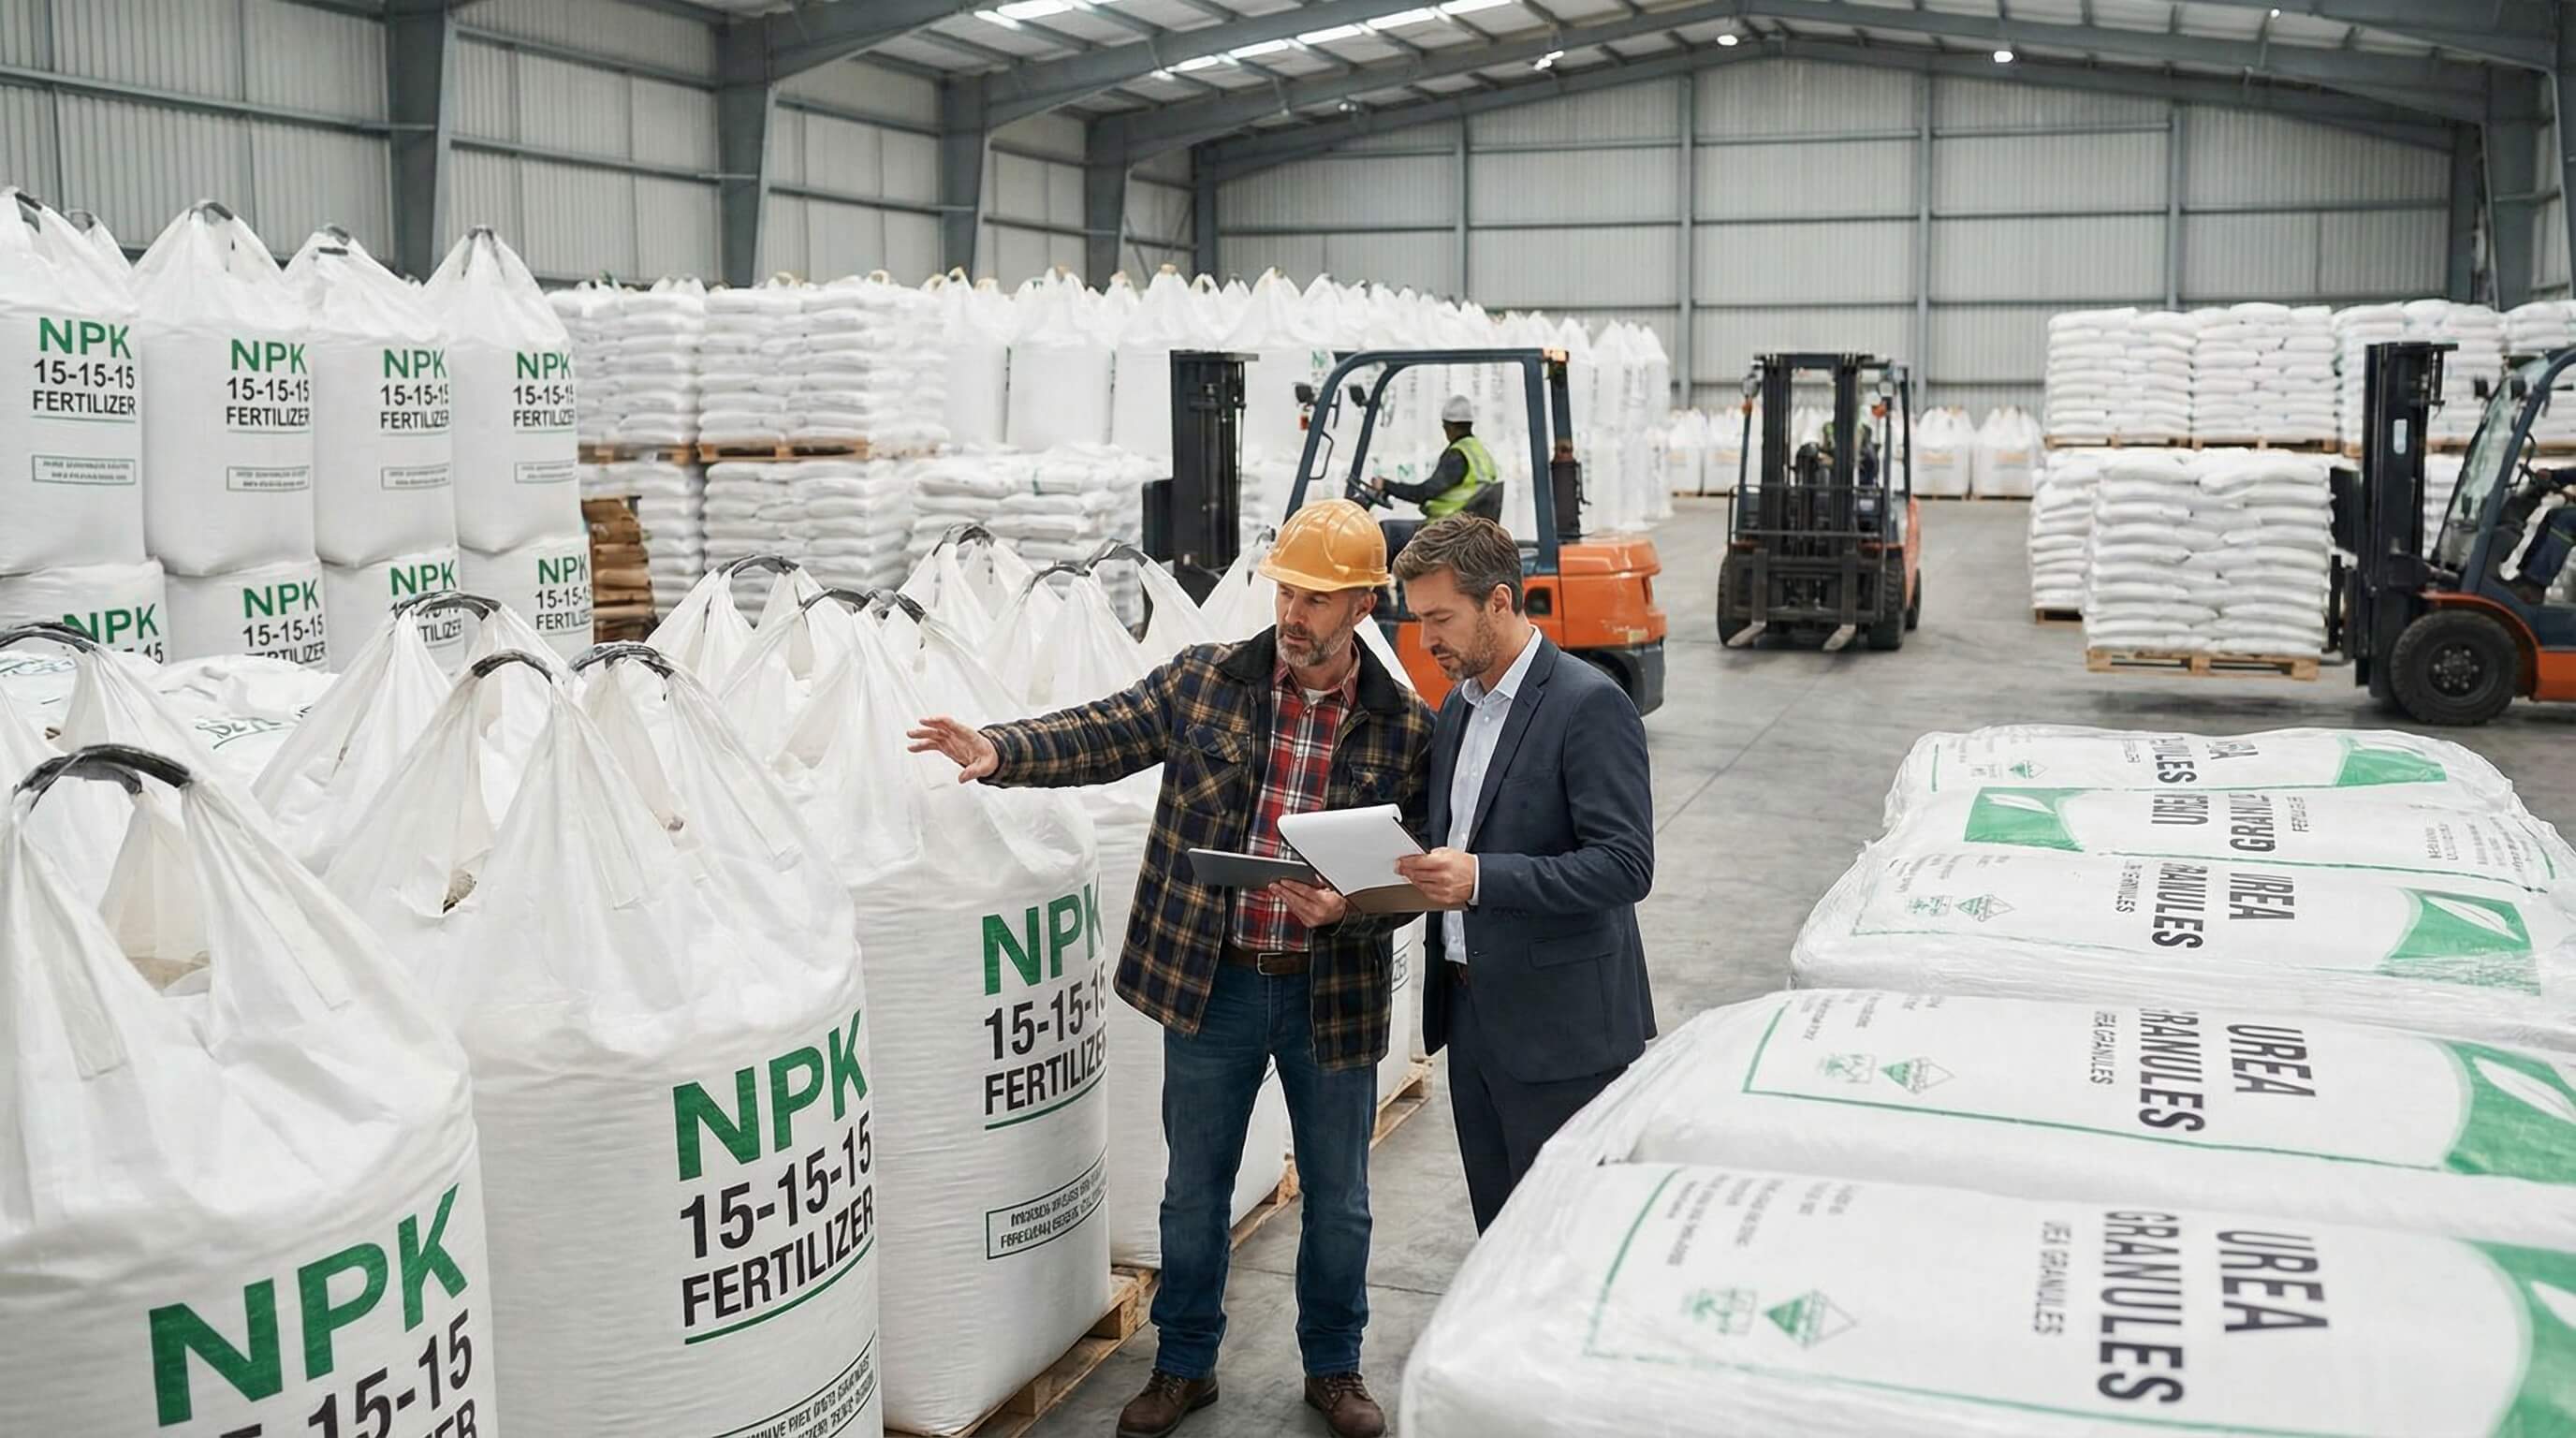
The global mineral fertilizer market has entered a phase of tense anticipation, creating both risks and strategic opportunities for Ukrainian farmers ahead of the 2026 spring planting season. While market activity in key regions like Brazil and Asia was temporarily muted due to seasonal holidays, major price indicators, particularly for urea, are showing an upward trend. This momentum is fueled by strengthening demand in the United States and the anticipation of results from a massive Indian tender, which could catalyze significant price volatility in the coming weeks.
For Ukraine's agricultural sector, this period is critical. According to the Ministry of Agrarian Policy and Food of Ukraine, securing planned fertilizer volumes is a key factor in achieving high yields, especially amid the volatility of global grain prices. The current market situation requires agricultural enterprises not just to monitor but to proactively plan their procurement to avoid both product shortages and financial losses from sudden price spikes.
Key Drivers of the Nitrogen Fertilizer Market
The primary market driver at present is India's RCF import tender. Expectations of high purchase prices by India are already heating the market, compelling suppliers from the Middle East and other regions to maintain high offers. The results of this tender will undoubtedly set a new price benchmark for the coming months, which will directly impact import costs for Ukraine.
Simultaneously, several conflicting trends are emerging on the supply side:
- Iranian Production: The gradual resumption of gas supplies to Iranian fertilizer plants promises an increase in urea volumes on the market. However, this factor is not expected to have a tangible impact until mid-April at the earliest, creating the prospect of price softening in the medium term.
- Logistical Challenges: Difficult ice conditions in the Baltic Sea continue to complicate logistics for Russian exporters. Although the arrival of additional icebreakers may partially stabilize the situation, the risk of supply delays remains, which supports prices in the Black Sea region.
- Geopolitical Tensions: The increased U.S. military presence near Iran adds an element of uncertainty to the market. While the crude oil market, a barometer of geopolitical risk, has so far reacted with restraint, any escalation could instantly affect freight and insurance costs, and consequently, the final price of fertilizers.
Analysis and Implications for Ukraine
The current market environment presents a strategic dilemma for Ukrainian farmers. The short-term forecast (the next 30-60 days) points to a probable firming of prices. Demand from the U.S. and Australia for March-April shipments, combined with the expected high prices of the Indian tender, creates a strong foundation for an increase. A wait-and-see approach in these conditions could lead to purchasing fertilizers at peak cost, right before fieldwork begins.
On the other hand, the prospect of increased supply from Iran and the potential entry of Chinese exporters into the market after mid-April could put downward pressure on prices. However, relying on this scenario is risky. Delays in production resumption or unexpected logistical hurdles could nullify this effect. According to forecasts from the FAO (Food and Agriculture Organization of the United Nations), the stability of global agricultural production in 2026 will largely depend on the timely and complete provision of resources to farmers, highlighting the risks of delayed procurement.
Navigating these complex conditions requires a deep understanding of the market and reliable supply channels. Experienced importers are already working to diversify their sourcing and optimize logistics routes to guarantee Ukrainian agricultural producers stable and timely deliveries, minimizing the impact of global volatility.
Strategic Outlook and Conclusion
The market situation will be extremely dynamic in the coming weeks. The announcement of the Indian tender results will be a signal for the entire market. Prices are expected to remain high or even rise in the period leading up to mid-April. This creates a narrow "window of opportunity" to make purchases at current, relatively stable prices.
For Ukrainian agricultural enterprises, the key task is risk management. Locking in prices for the required volumes of fertilizer for the spring season in the near future appears to be a sound strategy to hedge against price spikes and ensure guaranteed product availability. Postponing this decision may only be justifiable if one is prepared for significant volatility and potential supply disruptions at the height of the season.
Ensuring supply stability amid geopolitical and market turbulence is a priority. Collaborating with a reliable import partner who has access to global markets and can offer flexible logistics solutions is becoming not just an advantage, but a necessity for a successful season. To secure your farm's needs for the spring season at predictable prices, contact our specialists for a consultation and a personalized quote.